

How Does a 203k Loan Work, Start to Finish?
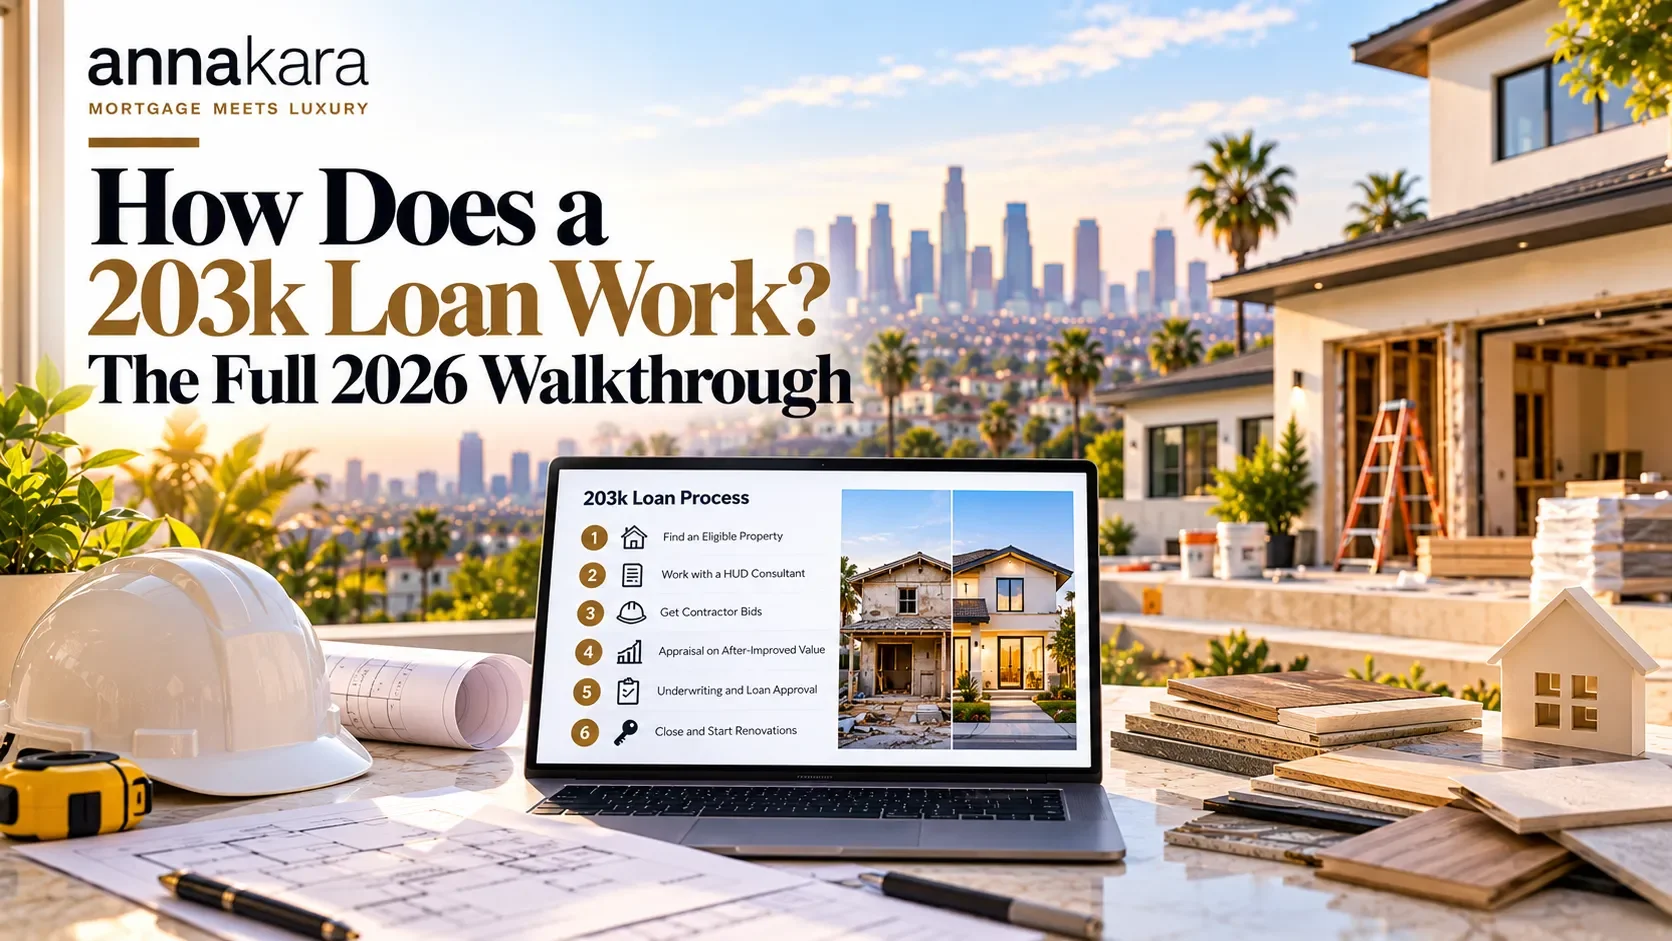
The 203k loan is one of the most misunderstood products in residential lending. Buyers hear that it lets them finance renovations along with a purchase, and they assume it works like a regular mortgage with a repair budget attached. It does not. The 203k has its own sequence, its own required players and a timeline longer than a conventional purchase. Knowing the mechanics before you make an offer protects you from the most common reasons these loans stall in escrow or after closing.
This post walks through the process in order, from finding the property to the final inspection. If you are still deciding whether a 203k fits your situation, start with my guide on who a 203k is actually for, and come back here for the step-by-step.
What a 203k loan actually is
The FHA 203k is a single mortgage that covers the purchase price and the renovation. The loan is sized on the home's projected value after the work is done, not on its condition today. If a home is listed at $480,000 and needs $90,000 in repairs, one loan can cover both, as long as the numbers fit FHA's limits and the appraiser supports the finished value. You can test a combined amount in the mortgage calculator before you start touring fixer-uppers. For the program overview, see our FHA 203k loan page.
Two versions: Limited and Standard
Limited 203k. For cosmetic and non-structural work, with a renovation budget up to $35,000. A HUD consultant is optional.
Standard 203k. For structural repairs, major system replacements and larger projects. The renovation must be at least $5,000, and a HUD-approved 203k consultant is required. The only ceiling on the renovation is the FHA loan limit for the county.
For Los Angeles County, the FHA loan limit for a single-unit home in 2026 is $1,249,125. The purchase price plus renovation costs together have to fit under that limit. Confirm the current figure with HUD's county limit lookup before you set a budget, because it changes every year.
Step 1: Find an eligible property
Not every home qualifies. The property generally must be a one-to-four unit residence that is at least a year old. Condos must be in an FHA-approved project. You must live in the home as your primary residence, so a 203k is not an investor loan. For two- to four-unit properties, you occupy one of the units. Mixed-use buildings can qualify when the residential portion is clearly the main use, and the renovation can't reduce the number of units.
Talk to me before you write an offer. The earlier I see the address, the sooner we know whether the property and the budget have a realistic path.
Step 2: Hire the HUD consultant (Standard 203k)
On a Standard 203k, you hire a HUD-approved consultant before the scope of work is final. The consultant visits the home, identifies required repairs, and prepares the Work Write-Up, which is the official scope of work, along with a cost estimate. The consultant's fee is set by a HUD fee schedule, generally runs from a few hundred dollars to around $1,000 or more depending on the project, and can be financed into the loan.
The Work Write-Up is not optional, and contractor estimates alone can't replace it. The lender builds the renovation portion of the underwriting on it. On a Limited 203k, the consultant is optional and the scope usually comes straight from contractor bids.
Step 3: Line up an approved contractor
Every contractor on a 203k project must be licensed in California and insured, and must submit a detailed bid that matches the Work Write-Up. The lender has to approve the contractor before closing. Do-it-yourself work is generally not allowed, and you can't act as your own contractor. Ask me about the specific rules for family members and for bonding, because lenders can add their own requirements.
This is the step that derails more 203k transactions than any other. Contractors who haven't worked with 203k draws, between-draw inspections or the timeline rules often drop out partway through or fail to get lender approval. Find one who has done it before you open escrow, not after you are in contract.
Step 4: The appraisal on after-improved value
The appraiser reviews the approved scope of work and estimates what the property will be worth once the work is finished to spec. FHA sizes the loan on the lower of:
110% of the after-improved value, or
the purchase price plus eligible renovation costs.
FHA then applies its 96.5% loan-to-value limit to that lower number, which is how the 3.5% minimum down payment works out. A worked example:
| Item | Amount |
|---|---|
| Purchase price | $480,000 |
| Renovation (per Work Write-Up) | $90,000 |
| Contingency reserve (10% of renovation, illustrative) | $9,000 |
| Project cost | $579,000 |
| 110% of after-improved value if the appraisal comes in at $600,000 | $660,000 |
| 110% of after-improved value if the appraisal comes in at $520,000 | $572,000 |
At a $600,000 after-improved value, the project cost is the lower number and governs. At $520,000, 110% of value is $572,000, which is below the $579,000 project cost, so the numbers don't work as planned. In that case you reduce the scope, increase your cash in, or renegotiate the price. This table leaves out FHA's upfront mortgage insurance premium, the consultant fee and other eligible costs, which affect the final figures.
Step 5: Closing and the renovation escrow
At closing, the loan funds in full. The seller is paid the purchase price, and the renovation money goes into an escrow account the lender controls. Contractors do not get the renovation budget at closing. They begin with their own capital, and some lenders allow a limited initial draw for materials, so ask about that early.
The escrow also holds a contingency reserve, a cushion for surprises such as hidden damage, which is typically somewhere in the range of 10% to 20% of renovation costs depending on the program and whether utilities are on. If you don't use it, the unused amount goes toward your principal at the end of the project.
If the home can't be lived in during construction, the loan can include up to six months of mortgage payments, subject to eligibility.
Step 6: Renovation and draw inspections
Work is paid in stages called draws. A Standard 203k allows up to five draws, and a Limited 203k usually has two, one around the midpoint and one at completion. Before each draw, the consultant or a HUD-roster inspector confirms that the completed work matches the approved scope, and the contractor is paid for finished work, not work in progress. That protects you and the lender, but it means the contractor needs enough working capital to carry the job between inspections.
Work typically has to start within about 30 days of closing, and the project generally has to be finished within six months, with extensions possible at the lender's discretion but not guaranteed. Delays from contractors, materials or scope changes need active management so they don't put the loan in default.
Step 7: Final inspection and wrap-up
When all the work is done and the final inspection is passed, the final draw is released. Any money left in the contingency reserve is applied to your loan balance. From there you pay one monthly payment, principal and interest plus taxes, insurance and mortgage insurance, on one FHA loan.
203k vs. a conventional renovation loan
| Factor | FHA 203k | Fannie Mae HomeStyle (conventional) |
|---|---|---|
| Minimum down payment | 3.5% | 3% to 5% |
| Typical minimum credit score | 580 (many lenders want 620 to 640) | 620 (640 preferred) |
| Mortgage insurance | Upfront premium plus annual premium; for life of loan if down payment is under 10% | PMI that can be removed at 80% loan-to-value |
| Renovation limit | Limited: $35,000. Standard: up to the FHA limit | Based on a percentage of the as-completed value |
| Occupancy | Primary residence only | Primary, second home or investment |
| HUD consultant required | Yes (Standard 203k) | No |
| Loan limit in LA County (2026) | $1,249,125 (FHA) | $1,249,125 (conforming high-balance) |
| Typical closing time | 45 to 60 days (Limited), 60 to 75 days (Standard) | Often a bit faster |
Program rules and lender requirements vary. Confirm current guidelines for your scenario.
If you are comparing both, the main trade-offs are the consultant and draw process on the FHA side against the stricter credit and down-payment rules on the conventional side. Our FHA loan page and conventional loan page cover each in more detail.
Conclusion
A 203k can be a smart way to buy a home in Los Angeles that needs work, especially when move-in-ready homes are priced at a premium. The process is longer and more structured than a standard purchase, but it is manageable when your lender, consultant and contractor all know the 203k rules. The most important step is the first one: bring me the property and the budget before you write the offer.
If you are looking at a fixer-upper and want to know whether a 203k can work for it, book a free consultation and I will walk through the numbers and the timeline with you. If you are ready to start, you can apply online. First-time buyers can also read about first-time homebuyer programs.
Anna Kara Inc., branch of Equity Smart Home Loans Inc. NMLS #1241473 | DRE #01924739. Equity Smart NMLS #856170 | DRE #01906808.
Disclaimer: This article is for general information only and is not a loan offer, commitment or financial advice. Examples are hypothetical and do not reflect current rates, fees or your situation. FHA and lender requirements, loan limits and program availability change and depend on your credit, income, property and loan approval. Equal Housing Lender.
Frequently asked questions
-
Usually longer than a standard purchase. Plan on roughly 45 to 60 days for a Limited 203k and 60 to 75 days for a Standard 203k, since the consultant visit, Work Write-Up, contractor approval and after-improved appraisal all have to happen first. Starting the consultant and contractor work early in escrow helps.
-
On a Limited 203k, the work is usually light enough that you can stay. On a Standard 203k involving structural work or major systems, the lender may require the home to be vacant. In that case, the loan can include up to six months of mortgage payments to help cover housing costs, subject to eligibility.
-
Eligible work typically includes roofing, HVAC, plumbing and electrical updates, kitchen and bathroom remodels, flooring, windows, accessibility improvements and structural repairs. Luxury items such as swimming pools and outdoor kitchens are generally not eligible. The Limited 203k covers non-structural work up to $35,000. The Standard 203k covers a much broader range of work, within the FHA loan limit.
-
Yes, for one-to-four unit homes, as long as you will live in one of the units. FHA loan limits for two- to four-unit properties are higher than for a single unit, which can help finance a duplex or triplex purchase and renovation. A 203k can’t be used for a pure investment property.